Articles / Edited private advice
Weekly Private Advice · Issue #3

GST going concern, temporary residency and capital returns

A going concern that was not one, a temporary resident’s foreign fund distributions and capital gains, and a capital return funded by external debt.

Written by
Andrew Lovett
Andrew Lovett
Founder, Tony.Online
6 October 2026 · 8 min read

About this series: We go through the edited private advice the Australian Tax Office publishes, select the most relevant and set out what it means. Each one records the Commissioner’s decision for a single taxpayer on a single set of facts, so it shows you the approach rather than giving you authority to rely on. Each summary carries its authorisation number. Andrew’s full disclaimer is at the foot of this article.

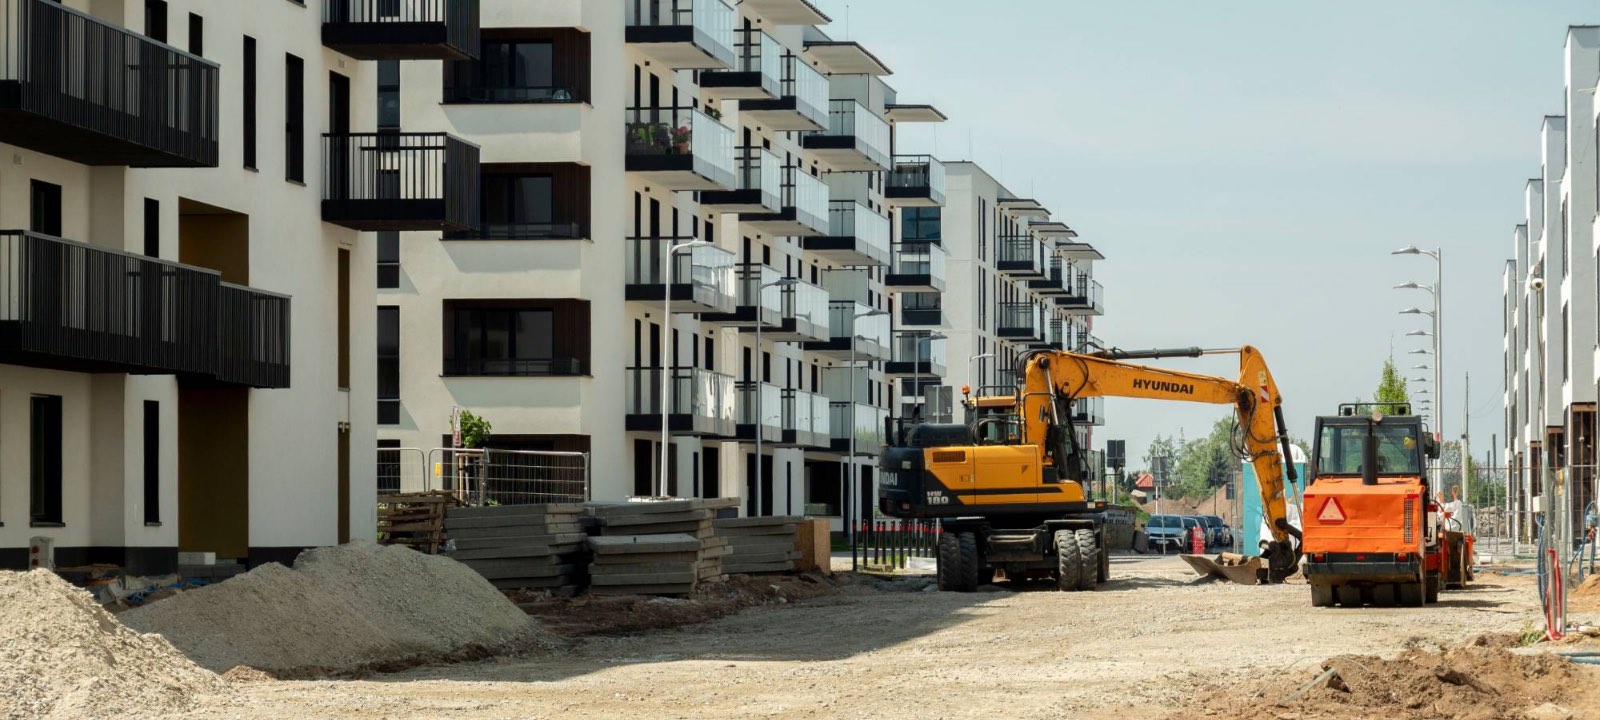
A partly finished apartment development, with an excavator and a roller on the unmade road in front of it
★  Advice of the week

1. GST: going concern on a development site

Authorisation 1052561083518 · 26 June 2026

Questions

Is the supply a GST-free supply of a going concern?

Answers

No.

Facts

A property developer bought a development lot under a contract accompanied by a future obligations deed. After the purchase, it carried out preliminary work: town planning, engineering and design, site clearing, and the erection of construction sheds. Before construction began, it agreed to sell the lot to a buyer who would complete the shopping centre development. The contract recorded the parties’ agreement that the sale was a supply of a going concern.

Explanation

The conditions: A supply of a going concern is GST-free only if the supplier provides all of the things necessary for the continued operation of an enterprise, and carries on that enterprise until the day of the supply. Goods and Services Tax Ruling GSTR 2002/5 adds that the parties’ own description of the transaction is not conclusive; the circumstances are examined objectively.

The identified enterprise: Following the Federal Court in Aurora Developments, the enterprise must first be identified as particular activities with content, not merely an objective. Until the content of the enterprise is isolated, it is not possible to say whether all necessary things were supplied.

Operation versus commencement: GSTR 2002/5 distinguishes carrying on an enterprise, which includes commencement and termination activities, from operating one. An enterprise that is only being commenced is not yet capable of being handed over in a state where the buyer could carry it on. Preliminary development activities, such as planning, design and site preparation, are commencement activities, not the operation of a development enterprise.

Applied here, the Tax Office disagreed with the developer’s submission. The sale was merely the sale of an asset, being land prepared for further development. The developer had not carried on an enterprise until the day of the supply, and had not supplied all things necessary for the continued operation of such an enterprise.

Implications

The going concern clause in the contract was not conclusive. The test is objective, and it failed here on both conditions.

For development sites, the line the ruling draws is between commencement and operation. Planning, design, approvals and site preparation sit on the commencement side. The main consequence here is that where going concern treatment fails, the sale is taxable, and the parties must look to the margin scheme or another concession instead. That changes the numbers for both sides and should be resolved before the contract, not after.

Also this week

Two more pieces of edited private advice. Open each one for the answer and the reasoning.

02

2. Temporary residency: foreign investment income and gains

Authorisation 1052559666750 · 26 June 2026

Questions

  • Are they a temporary resident for tax purposes?
  • Are distributions from the foreign funds included in their assessable income?
  • Are capital gains on disposing of units in those funds included?
Show the answer and reasoning

Answers

Yes to the first. No to the second and third.

Facts

The taxpayer arrived in Australia with their family on a Special Category Visa (subclass 444), intending to relocate permanently. They are semi-retired and hold foreign investments, predominantly exchange traded funds listed overseas.

Explanation

The status: A temporary resident, as defined in section 995-1 of the Income Tax Assessment Act 1997, holds a temporary visa, and neither they nor their spouse is an Australian resident within the meaning of the Social Security Act 1991. That definition turns on citizenship, a permanent visa or protected Special Category Visa status. The ruling accepted that the taxpayer was an Australian resident for tax purposes, satisfying the resides test and the 183-day test. But because neither they nor their spouse were citizens, permanent visa holders or protected Special Category Visa holders, they were also a temporary resident. The two statuses coexist.

Foreign income: Under Subdivision 768-R, section 768-910, ordinary and statutory income from foreign sources is not assessable when derived by a temporary resident, other than employment income and certain employee share scheme amounts. Distributions from the foreign funds were therefore excluded.

Foreign capital gains: Under section 768-915, a capital gain or loss made by a temporary resident is disregarded if it would have been disregarded under Division 855 for a foreign resident. Division 855 disregards gains on assets that are not taxable Australian property. Units in widely held, listed funds are generally not taxable Australian property, unless they constitute an indirect Australian real property interest. That requires passing both the non-portfolio interest test and the principal asset test. The ruling concluded that the taxpayer’s fund units were not taxable Australian property, and that the gains were disregarded.

Implications

Temporary residency decouples foreign investment income from Australian tax, but only while the status lasts. In practice, the status ends on permanent residency or citizenship, and from that point foreign income and gains become taxable in Australia.

The capital gains exemption has a boundary that needs to be checked on a fund-by-fund basis. Widely held listed units are generally outside the scope of taxable Australian property, but a fund concentrated in Australian real estate can cross into it through the two tests the ruling cites. In practice, check the portfolio composition before assuming the exemption applies, and check it again when the portfolio changes.

03

3. Capital return funded by external debt

Authorisation 1052564431694 · 2 July 2026

Questions

  • Will any part of the capital return be a dividend under its definition?
  • Will the Commissioner make a determination that any part of the capital return is deemed to be a dividend paid out of profits (relating to streaming)?
  • Will the Commissioner make a determination that any part of the capital return is deemed to be a dividend paid out of profits (relating to tax benefits)?
  • Will the Commissioner impose a debit to the franking account in respect of the capital return?
Show the answer and reasoning

Answers

No to all four.

Facts

The head company of a consolidated group proposed to issue external debt to fund a pro rata return of capital to its shareholders, debited entirely to its share capital account. The group had insufficient retained earnings to fund the return, a history of paying dividends, and no previous external debt.

Explanation

The dividend definition: Paragraph (d) of the definition in subsection 6(1) excludes money paid to shareholders where the amount is debited against the company’s share capital account. The account here was not tainted within the meaning of Division 197 of the Income Tax Assessment Act 1997, because only genuine share capital contributions had been credited to it. The exclusion was therefore available in full.

Section 45A — streaming: Section 45A targets the streaming of capital benefits to some shareholders and dividends to others. The return was pro rata, in proportion to each shareholder’s interest, with no disposal or cancellation of shares. With no advantaged and disadvantaged shareholders, the streaming condition was not met.

Section 45B — purpose: Section 45B requires a scheme, a capital benefit, a tax benefit, and a more-than-incidental purpose of obtaining the tax benefit. The first three were present: the return was a capital benefit, and receiving it as capital rather than as an assessable dividend was a tax benefit. The purpose element failed. The Tax Office weighed the factors in subsection 45B(8), guided by Practice Statement PS LA 2008/10. The group had a commercial rationale in its gearing ratio, with debt materially cheaper than equity. There were insufficient retained earnings to fund the return. There were no unrealised profits that could have been distributed as dividends, in light of the Full Federal Court’s decision in Hicks. The pro-rata structure, while not determinative on its own, did not suggest a tax purpose. The timing corresponded with the group’s review of financing models.

Franking debit: The fourth question followed the third. With no section 45B determination, there is no debit to the franking account under subsection 45C(3).

Implications

In this case the whole return was debited to an untainted share capital account, which took it outside the dividend definition, so whether the account is untainted is the first question.

Section 45B turned on purpose, and the purpose question turned on the facts presented. The Tax Office accepted the commercial rationale on those facts: a financing review, a gearing objective, and a genuine cost-of-funds advantage. The practice statement’s default position is that a distribution to increase gearing is generally attributed proportionately to share capital and retained earnings. The decisive facts were the absence of retained earnings and unrealised profits. The advice does not address a group with ample retained earnings, where the practice statement’s default position would apply.

For shareholders, the ruling notes that the return triggers a capital gains tax (CGT) event G1, with the discount available to eligible shareholders on any resulting gain, or a reduction in the cost base of the shares where no gain arises.

Disclaimer: We believe this information is correct at the time of publication. It is general in nature, for guidance only, and is not intended as personal advice. It should not be relied upon without professional advice about your direct circumstances. No responsibility can be accepted by any publisher, author, editor, contributor, or consultant for loss directly or indirectly arising from any person acting or refraining from acting wholly or partly upon the material in this publication, or for any error, broken link, or omission from the publication. Edited private advice is published by the Tax Office in modified form. It is based on private rulings that apply only to the taxpayer who applied. It is not a public ruling and cannot be relied upon by another taxpayer. This publication is general information for Australian tax professionals only; it is not tax, financial, or legal advice. It is not suitable for other people.

Andrew Lovett
Written by
Andrew Lovett
Founder, Tony.Online · Director, Lovetts · Registered Tax Agent

Two decades working across every entity type, and a computer-science background that turned into Tony.Online, the tireless second analysis he always wished he had.

More reading

View all →

Get the advice every week.

The week’s ATO edited private advice, easy to read. One email, every Tuesday. No spam, unsubscribe anytime.